For the first nine months of 2026, VietCredit recorded pre-tax profit of VND 1,558.6 billion, nearly double that of the same period last year. Total assets and outstanding loans both more than doubled after one year. Simultaneously, service fees and provisions also increased in line with the scale of operations.
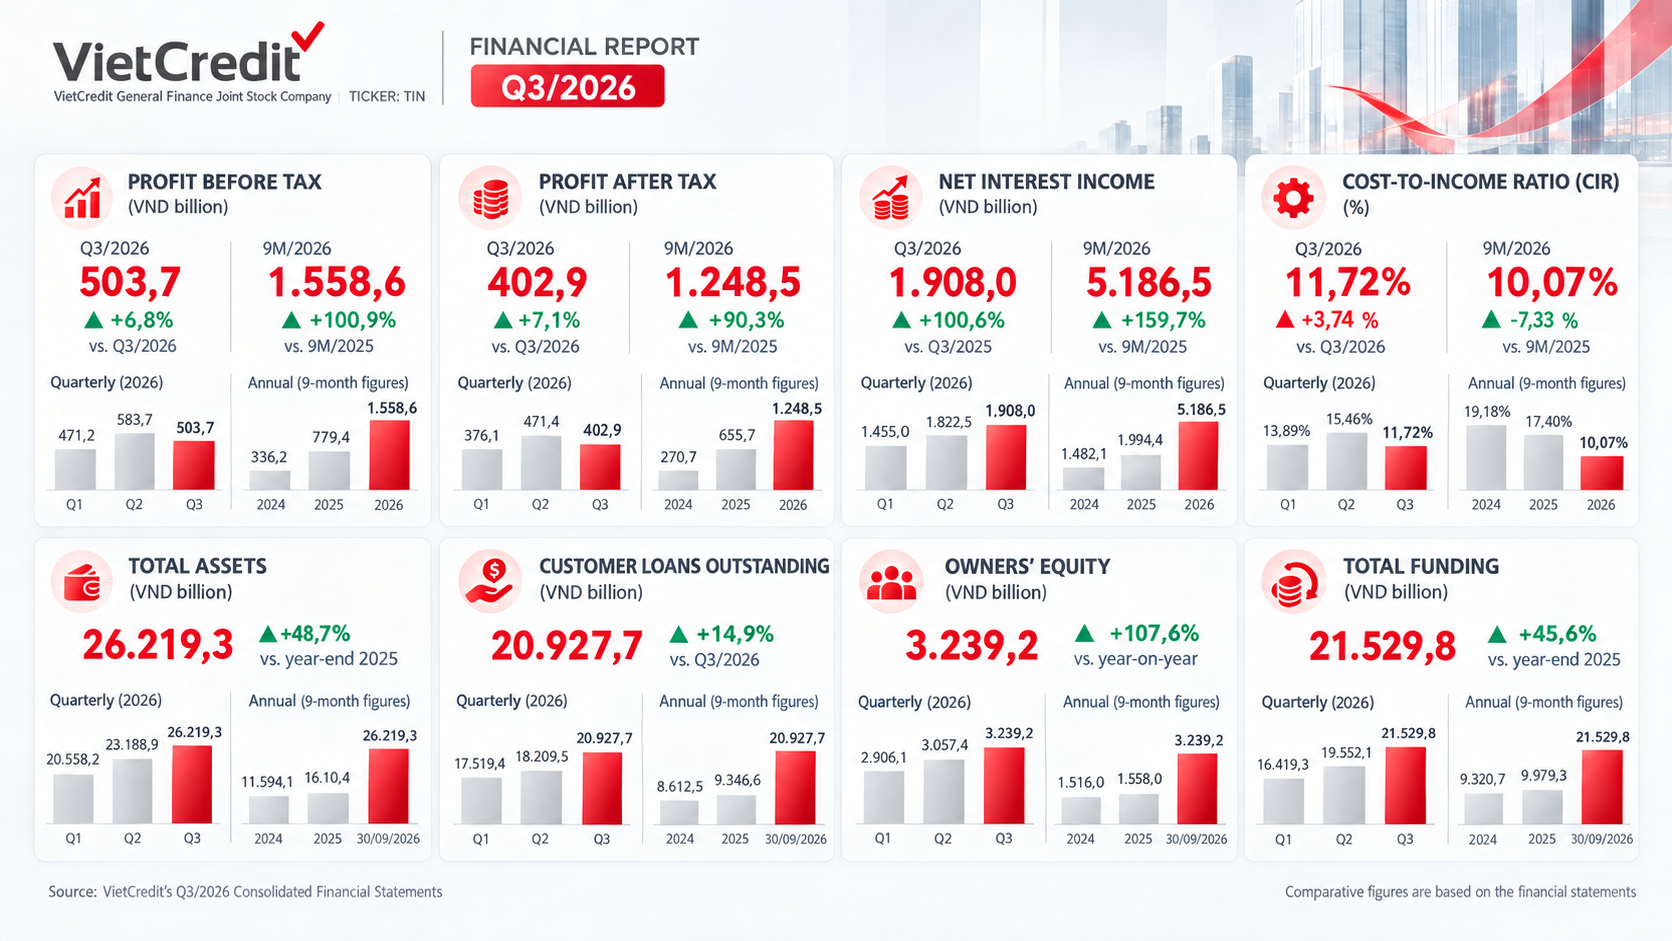
Profits for the first nine months nearly doubled, and net interest income increased by almost 160%.
VietCredit Joint Stock Company (UPCoM: TIN) has just announced its financial report for the third quarter of 2026.
For the first nine months of the year, pre-tax profit reached VND 1,558.6 billion, nearly double the VND 779.4 billion recorded in the same period of 2025. After- tax profit reached approximately VND 1,248.5 billion, an increase of over 90%.
In the third quarter alone, VietCredit’s pre-tax profit reached VND 503.7 billion and after- tax profit reached VND 402.9 billion, a continued increase compared to VND 376.6 billion in the previous quarter.
Growth continued to be driven by core lending activities. Net interest income in the third quarter alone reached approximately VND 1,908 billion, an increase of over 100% compared to the same period last year and a further increase compared to the second quarter. For the first nine months of the year, net interest income reached approximately VND 5,186.5 billion, an increase of nearly 160% compared to the same period in 2025.
According to the financial statement notes, interest income from customer lending activities in the first nine months reached over VND 5,388 billion, an increase of approximately 167%, corresponding to the rapid expansion of the credit portfolio. Therefore, net interest income was the main contributor to the Q3 profit results, largely offsetting provisions and losses from service activities incurred during the period.
For the first nine months of the year, total operating income reached approximately VND 4,118.2 billion, a 160.3% increase compared to the same period last year. This figure is lower than net interest income due to a decrease in net revenue from service activities, while costs related to Digital Lending and partner platforms increased proportionally with scale.
Meanwhile, operating expenses amounted to approximately VND 414.8 billion, a 50.7% increase year-on-year. Several administrative expenses, taxes, fees, and transaction-related costs increased in line with business activity. Because total operating income increased faster than operating expenses, the cost-to-income ratio (CIR) improved significantly, reaching approximately 10.07%, up from 17.4% in the same period last year.
Total assets exceeded 26.2 trillion VND, outstanding loans exceeded 20 trillion VND for the first time, and the CIR was around 10%.
As of September 30, 2026, VietCredit’s total assets reached approximately VND 26,219 billion, equivalent to 2.26 times the same period last year and an increase of nearly 49% compared to the beginning of the year. In the third quarter alone, the asset size increased by more than VND 3,000 billion.
The main driving force continued to come from lending activities. Outstanding customer loans reached nearly VND 20,928 billion, an increase of over 124% compared to the same period last year and 14.9% compared to the end of the second quarter, thus exceeding the VND 20,000 billion mark for the first time. Total assets reached VND 26,219 billion, of which outstanding customer loans amounted to nearly VND 20,928 billion, showing that asset growth continues to be closely linked to lending activities.
Besides the individual customer segment, which remains the dominant focus, VietCredit’s loan portfolio is expanding to include various customer groups and products such as household businesses, small enterprises, credit cards, buy now pay later loans, and secured loans. According to the financial report, outstanding loans to economic organizations at the end of the third quarter reached approximately VND 2,772 billion, nearly 3.8 times higher than at the end of 2025 and accounting for over 13% of total outstanding loans, demonstrating an increasing diversification of the credit portfolio.
Capital increases along with the scale of operations.
Along with asset growth, VietCredit’s equity at the end of September reached approximately VND 3,239 billion, more than double that of the same period last year. Undistributed profits reached over VND 2,075 billion, supplementing internal capital for business operations.
Total capital mobilized from credit institutions, customer deposits, and the issuance of securities reached approximately VND 21,530 billion, an increase of more than 2.3 times compared to the same period last year and about 45.6% compared to the beginning of the year. Of this, certificates of deposit accounted for over VND 13,619 billion.
The simultaneous increase in both fundraising and equity capital during the loan expansion period has provided VietCredit with additional resources to finance asset growth, while maintaining capital balance as its operations grow.
Provisions increase with outstanding loans.
The rapid increase in outstanding loans led to higher provisions for bad debts. Credit risk provisioning costs in the third quarter alone reached approximately VND 845.8 billion; the cumulative figure for the first nine months exceeded VND 2,144 billion. The fact that pre-tax profit still reached VND 1,558.6 billion despite large provisions suggests that profit growth mainly came from expanding core income, rather than from reducing credit costs.
The overall non-performing loan ratio at the end of Q3 2026 was approximately 6.75%. With customer loan balances increasing by over 124% year-on-year, the size of provisions also increased in line with the expansion of the portfolio. As credit growth continues at a high rate, the quality of new loans, especially in rapidly growing products, will require more time to fully reflect the overdue and non-performing loan indicators in subsequent periods.
Debt collection activities also continued to improve: collection from risk-managed debts in the first nine months reached approximately VND 58.5 billion, an increase of over 135% compared to the same period last year. This collection contributed to offsetting some of the risk costs incurred during the portfolio expansion process.
Expand your digital distribution channels.
As of the end of Q3/2026, VietCredit continues to maintain cooperation with existing partner channels such as MoMo, Zalo, Viettel Money, Grab, TikTok, Misa, and KiotViet. In addition, the company has recently added several new cooperation models, such as deploying consumer loans on VietinBank iPay using VietCredit’s own capital, expanding business loans through the Sapo platform, and launching the TINCard 3-in-1 digital domestic credit card in collaboration with Napas and the Dien May Xanh and The Gioi Di Dong ecosystems.
In the latter part of the year, the company continues to develop digital financial products and expand its partner ecosystem in a controlled growth direction, promoting the application of technology, AI, and data in operations, product development, and risk management to improve operational efficiency. Therefore, the strategic direction is to pursue selective credit growth coupled with portfolio quality control.
Expanding digital channels allows VietCredit to reach more customer groups through its partners’ existing platforms and user bases, but it also makes partner costs and the quality of new loans variables that need to be monitored as transaction volumes increase.
In the fourth quarter, key factors to watch include not only loan growth rates and profits, but also the quality of new loans, provisioning levels, cost of capital, and counterparty distribution costs.